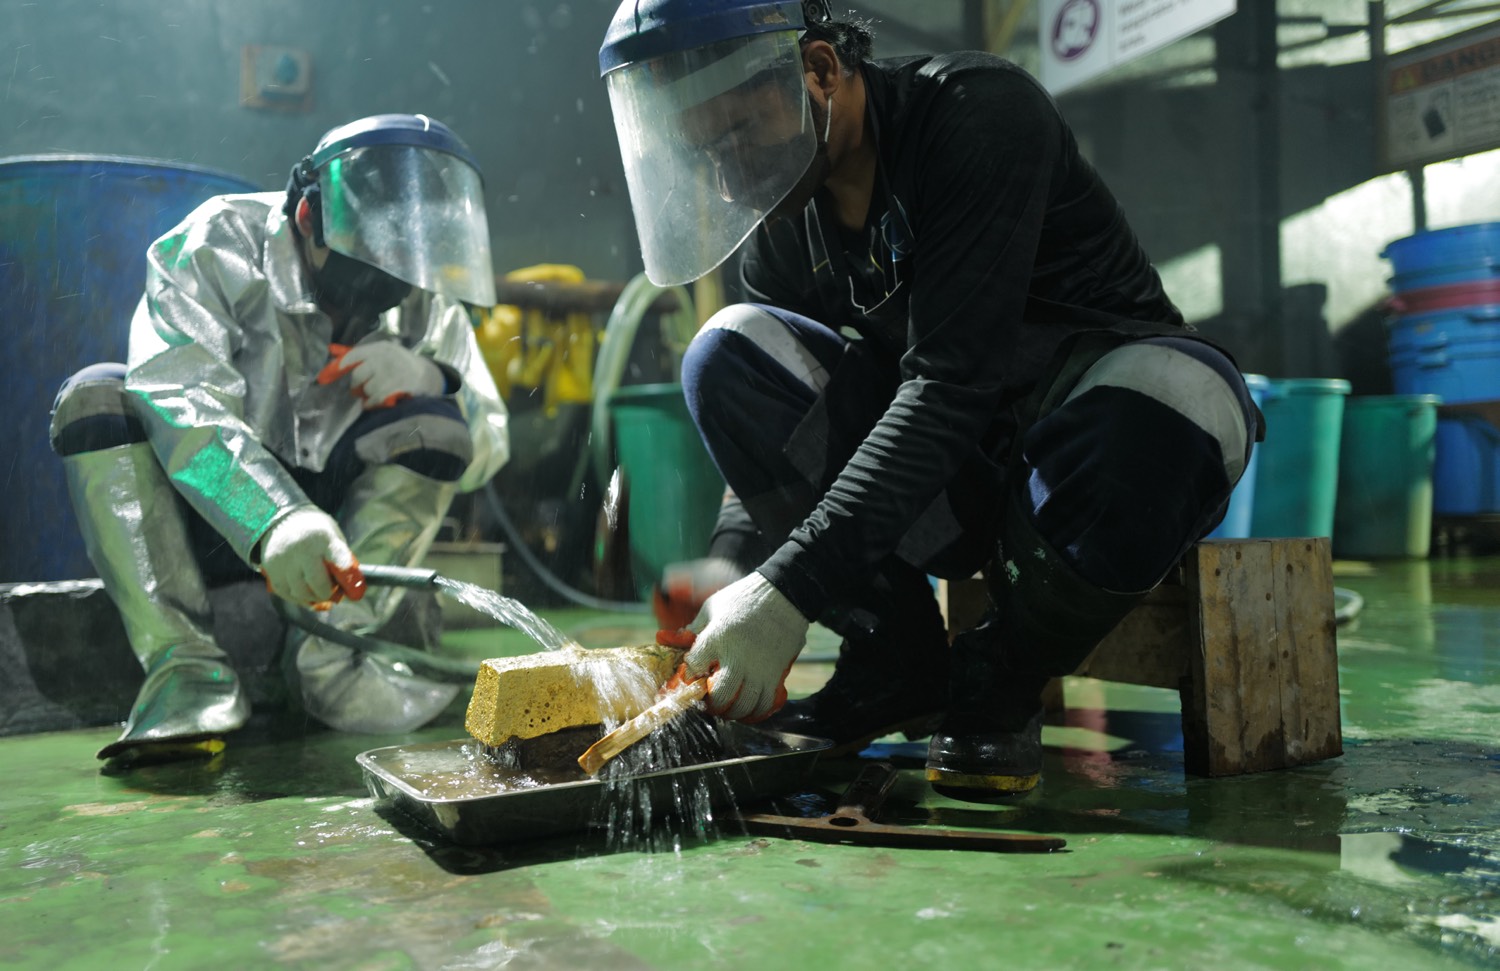
Perseus's Nyanzaga build is advanced. The pre-production bill still matters.
The construction estimate is unchanged, but accelerated mining raises total forecast pre-production spending. September cash also predates October's dividend.
 Global Mining & Metals · OCTOBER 29, 2026
Gold is the fear gauge. Silver and the PGMs are half-industrial tells.
Model demonstration: news, volume and equity inputs are illustrative.
| Gold US$/oz · Fetched futures · 2026-10-29 | 4,041 | -12.7% 6M | +1.5% 1Y | 61 | |
| Silver US$/oz · Fetched futures · 2026-10-29 | 52.77 | -28.2% 6M | +12.0% 1Y | 55 | |
| Platinum US$/oz · Fetched futures · 2026-10-29 | 1,501 | -24.1% 6M | -4.8% 1Y | 44 | |
| Palladium US$/oz · Fetched futures · 2026-10-29 | 995 | -34.8% 6M | -29.1% 1Y | 26 |
What the spot price won't tell you: the shape of the futures curve (who's paying up for metal now) and where warehouse stock is heading. Figures are indicative until a live LME/CME feed is wired.
Illustrative example — not current exchange quotes. This curve does not update automatically.
Deferreds trade over spot — comfortable supply and positive carry. A long rolling the front bleeds the spread.
Sample data for explaining term structure.
The construction estimate is unchanged, but accelerated mining raises total forecast pre-production spending. September cash also predates October's dividend.
KCGM's tie-in is complete, but commissioning, growth spending and hedge deliveries still shape Northern Star's cash generation. The September report sets a measurable test.
September's 2Mtpa annualised mining rate is encouraging. The interim ventilation solution and Westgold's dated treasury figures explain both the opportunity and the remaining work.
DRDGOLD's September-quarter update provides a concrete gold cash-return case outside conventional new-mine development. Yield, processing costs and infrastructure spending still determine the economics.
Evolution’s September report shows substantial mine cash generation. Group expenses, working capital, tax and a dividend paid after quarter-end explain why the headline is only a starting point.
 ASX:TM1
Terra has released the Southwest assays and price-query response promised during its halt. The near-surface results are encouraging, with a publication qualification that investors should retain.
ASX:TM1Terra requested a halt for an ASX price-query response and exploration results. Southwest’s published drilling, access and funding give investors a constructive case to assess.
Barton has completed Tunkillia’s upgrade drilling. Its next study needs to show whether richer early feed improves the economics, and how development will be funded.
Sandstone now holds 3.6 million resource ounces. Brightstar’s escrow cash and 12.5% bond explain why delivery matters as much as discovery.
MGX has substantial cash and investments. A dated balance-sheet comparison tests the discount, the gold exposure and the capital still needed.
Gold has slipped from last week's three-month high to about $4,336/oz as traders whipsaw between a softening US labour market and a Fed chair signalling he may raise rates to fight sticky, war-fed inflation before the September 16 decision.
ASX:TM1TM1 last printed A$0.23, 38% under the February placement and 51% off the 52-week high. The till still holds most of an $85m raise, five rigs are turning at Southwest, and the register is a short list of resource houses. That is overhang. It is not a gold-stock bargain.
Barton Gold (ASX:BGD) has ridden record bullion — gold near US$4,600/oz and the ASX Gold Index's best session of the year — back toward its 52-week high, while its own Challenger and Tunkillia drilling keeps delivering grade to justify the re-rate.
Brightstar Resources (ASX:BTR) has more than doubled off its August low, and this week's record intercepts at the Two Mile Hill-Shillington deposit — including 19m at 24.3g/t gold — gave the run something to point to besides a hot gold tape.
Right Resources (ASX:RRE), a ~$10m-market-cap explorer at Tumbarumba, NSW, is chasing a Reduced Intrusion-Related Gold System with CODES-backed geology — and found a coherent, open-ended tungsten anomaly next door in a market where China controls 85% of supply.
With gold near record highs around US$4,200/oz, Evolution Mining swung to net cash and kept paying dividends, while peers Northern Star and Newmont return cash through buybacks.
Barton Gold completed an oversubscribed A$25.9m institutional placement at A$0.85 per share, led by Canaccord Genuity and MST Financial, to fund a Challenger DFS, Tunkillia studies and Tolmer drilling in South Australia's Gawler Craton.
With gold off its January peak but still above $4,300/oz, the majors are spending record free cash flow on deals — royalty roll-ups, regional consolidation and reserve replacement — rather than the drill bit.
A yieldless rock is near record highs while real assets are supposedly out of fashion. Gold isn't telling you about gold. It's telling you what the smart, nervous money thinks about everything else.
| Operation | Country | Owner | Stage |
|---|---|---|---|
| Tunkillia / Tarcoola | Australia | Barton Gold | Development |
| Sandstone | Australia | Brightstar Resources | Development |
| Pilot Project | Australia | Right Resources | Exploration |
| Carlin Trend / Nevada | United States | Nevada Gold Mines (Barrick/Newmont JV) | Producing |
| Kalgoorlie Super Pit | Australia | Northern Star Resources | Producing |
| Mogalakwena | South Africa | Anglo American Platinum | Producing |