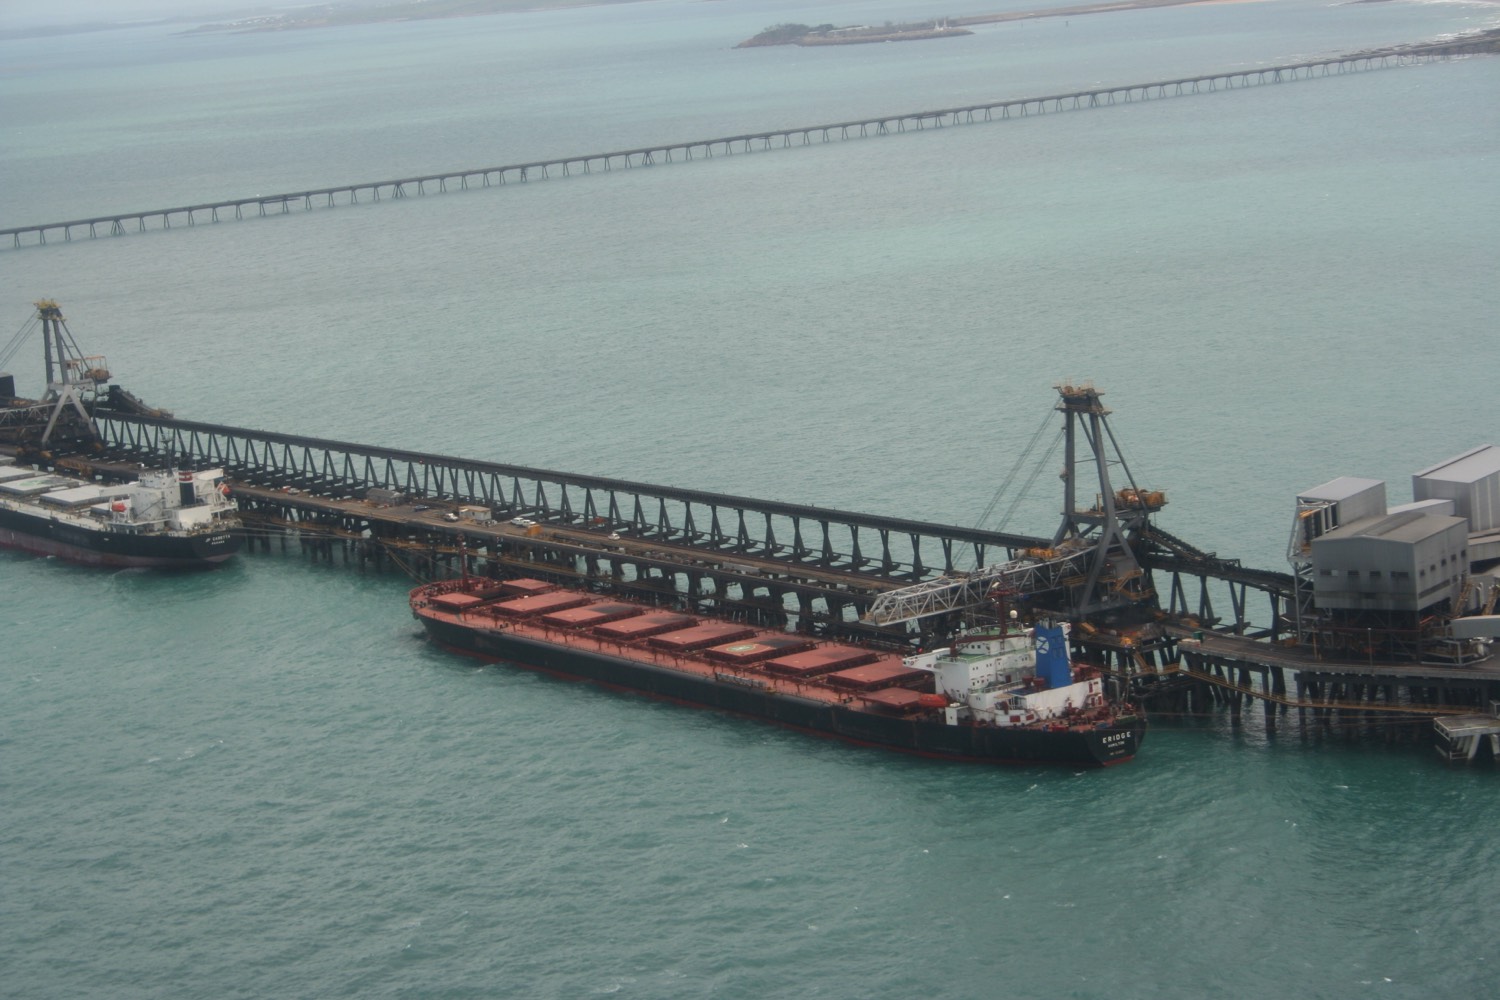
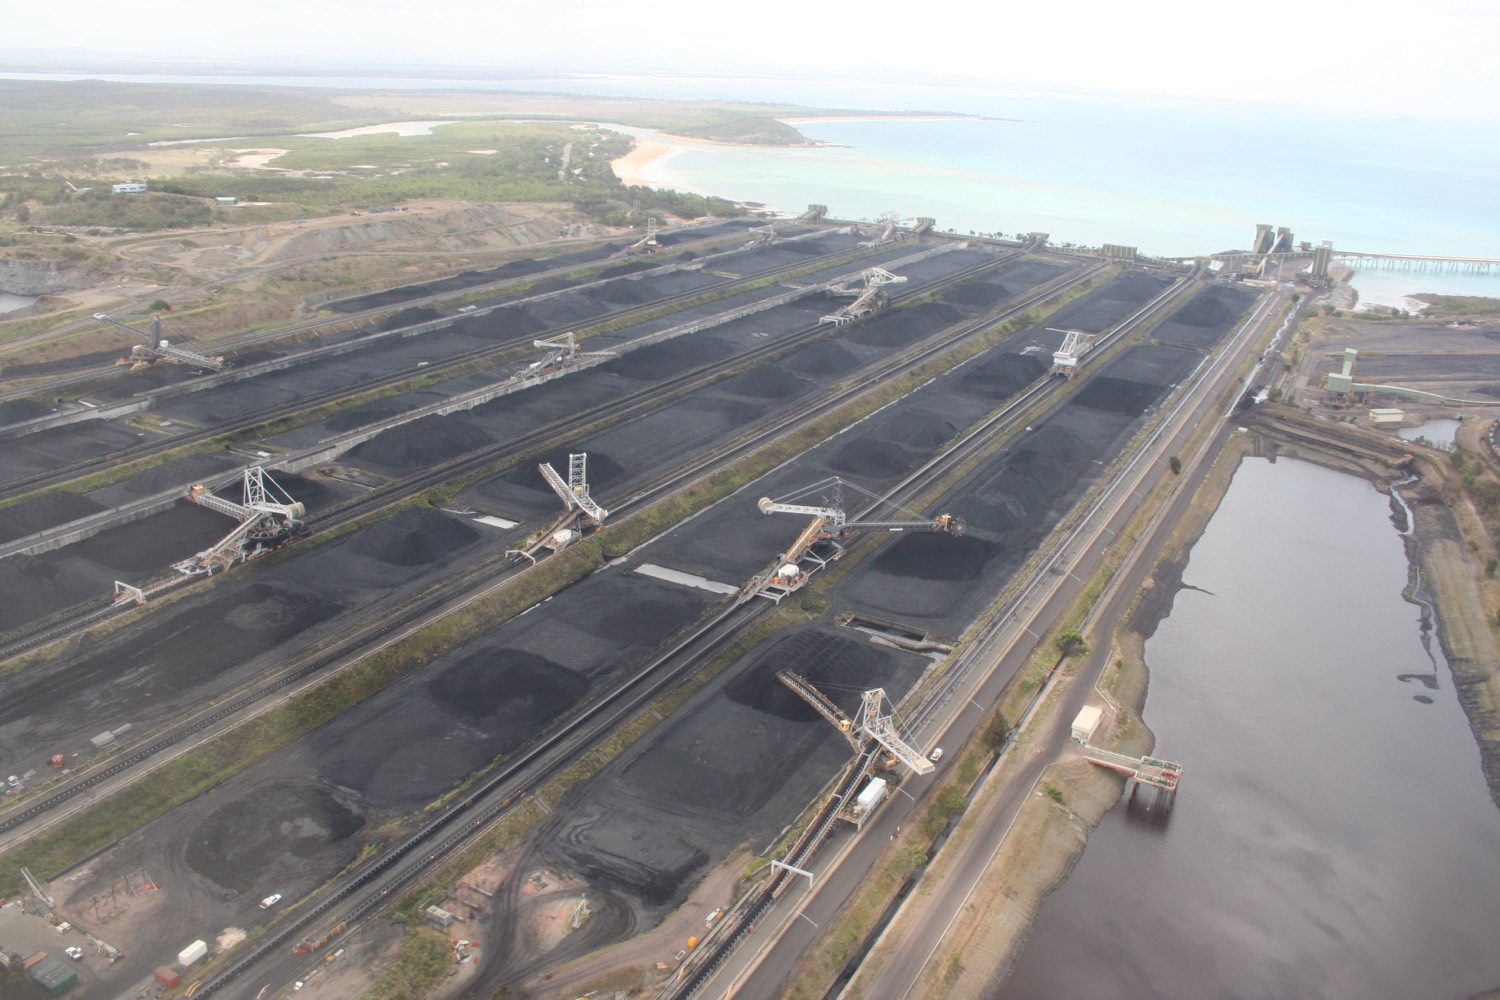
Whitehaven's coal has reached the stockpile. Shareholders need it on a ship.
September production rose, but port outages delayed sales and lifted inventories. Whitehaven also has acquisition payments ahead of its shareholders.
 Global Mining & Metals · OCTOBER 29, 2026
Graphite is the anode nobody photographs. It's also a chokepoint.
Model demonstration: news, volume and equity inputs are illustrative.
| Graphite (flake) US$/t · Illustrative sample · 2026-06-16 | 780 | +6.0% 6M | +10.0% 1Y | 55 |
September production rose, but port outages delayed sales and lifted inventories. Whitehaven also has acquisition payments ahead of its shareholders.
Anglo American's coal output has recovered, and its Dhilmar sale remains targeted for early 2027. The maximum consideration includes a substantial price-linked earnout.
New Hope proposes to buy the rest of Malabar with shares. Maxwell offers a credible growth opportunity, but the return depends on ramp-up costs, debt and cash earned per enlarged share.
Peabody’s June accounts show why coal investors need to distinguish cash generation, capital payments and collateral releases before calling a stock deep value.
Kestrel adds steelmaking coal and acquisition debt to Yancoal. The completion notice confirms the deal, but leaves investors without a full settlement cash bridge.
The High Court setback leaves the expansion in doubt, while the existing mine can operate until 2032. The economic argument deserves a serious hearing alongside the emissions case.
 ASX:SMR
Stanmore Resources' first-half 2026 accounts are a cash-machine print dressed as a statutory loss: saleable production in line, realised prices up US$21/t, operating cash in, and a skipped interim. The number that actually moved is the royalty — US$109m to Queensland, against a US$44m loss for equity.
ASX:SMRStanmore Resources and Whitehaven Coal posted strong met-coal cash flow and kept paying shareholders through a soft 2025–26, even as ESG financing policies keep lenders away from coking coal.
White Energy (ASX:WEC) proposes to acquire Nathan Tinkler's private Oceltip Coal 2 for $4m cash and install him as executive chairman, funded by a $15m raise at 6c, in a return to coal development.
The anode gets none of the glamour and most of the leverage. China dominates natural flake, synthetic graphite and — crucially — the processing in between. Building a Western anode supply chain is harder than building a mine.
| Operation | Country | Owner | Stage |
|---|---|---|---|
| Balama | Mozambique | Syrah Resources | Care & Maintenance |
| Vidalia (anode plant) | United States | Syrah Resources | Producing |